

Compound Interest
Interest on interest is the whole idea. Over twenty years it does more work than the original deposit, and this shows how much more.
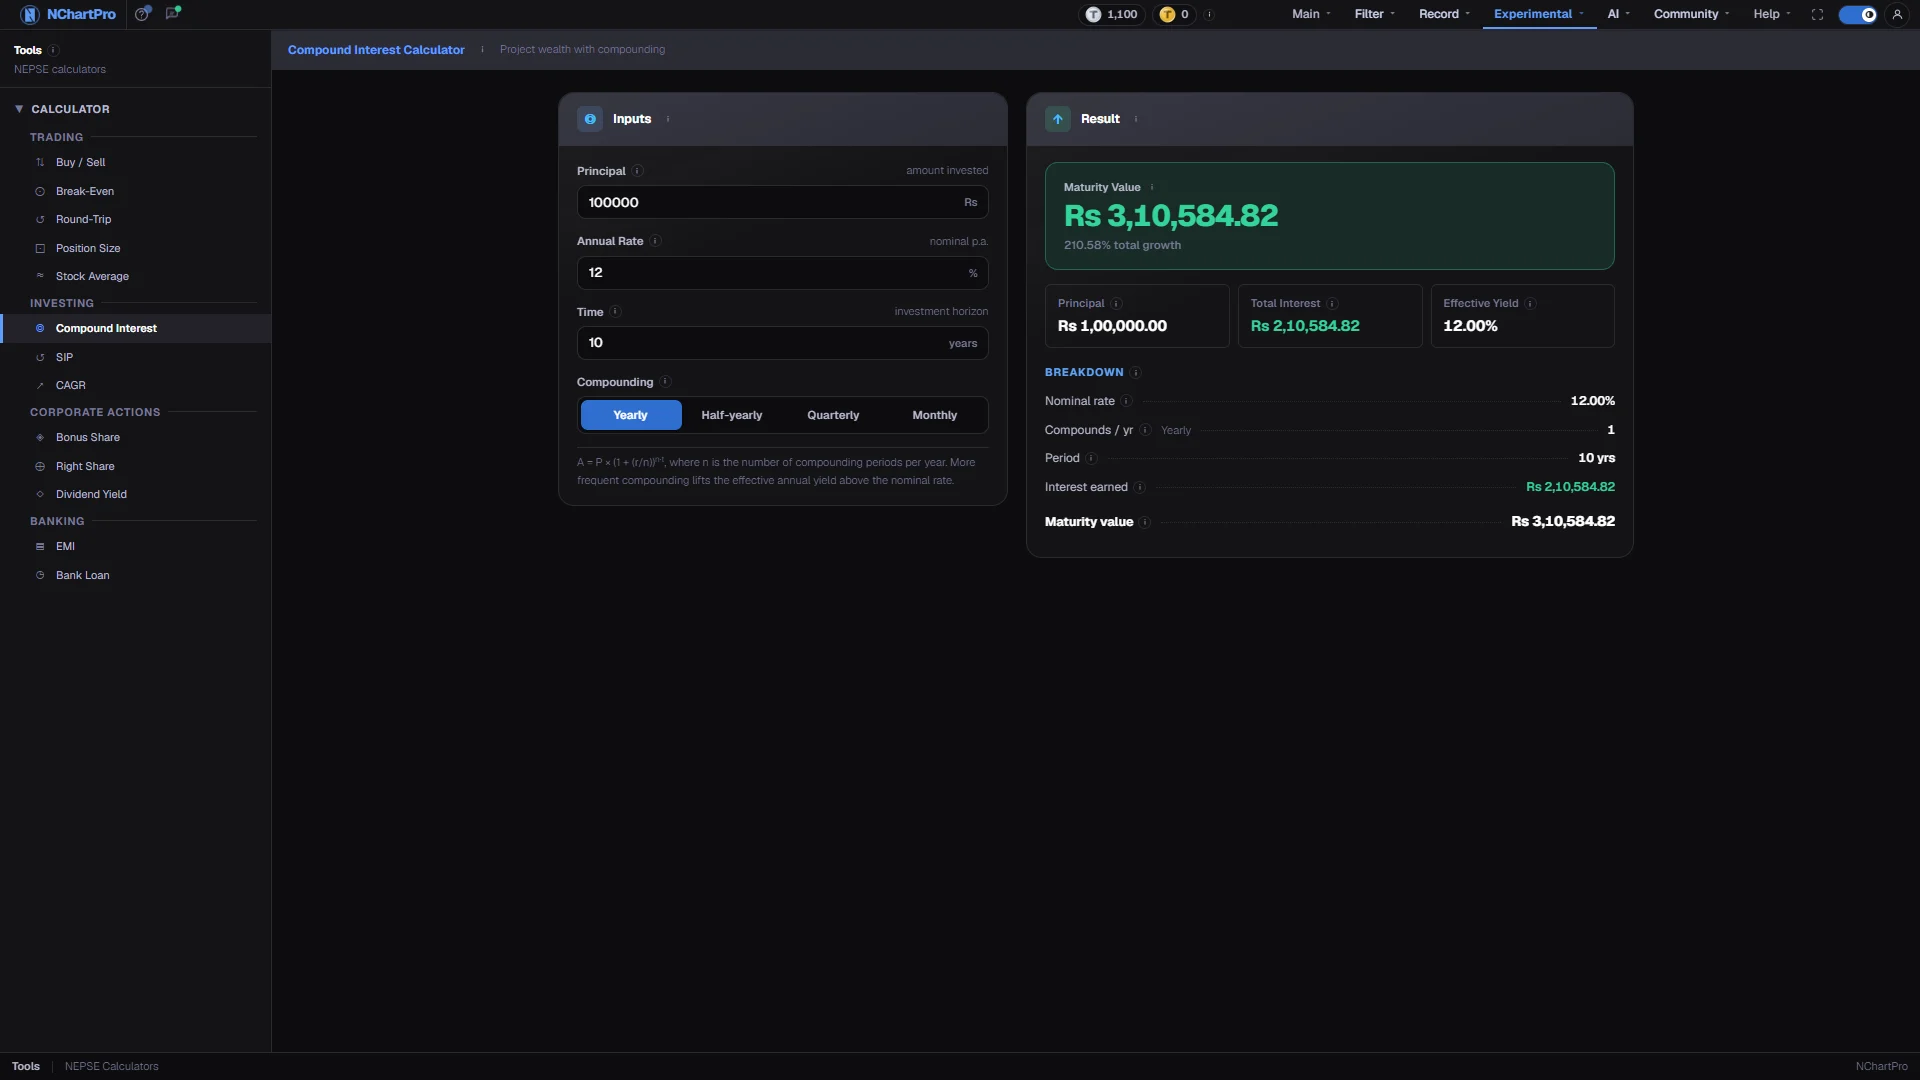
What this page is
Four inputs: a one-time principal, an annual rate, a number of years, and how often the interest is added back. The result is the maturity value, split into your own money and the interest it earned.
The effective yield chip is the quiet lesson. At the same headline rate, interest added monthly produces a higher real annual return than interest added once a year.
Why it helps you
- Not a trading tool. There is no market, no price and no position on this page.
- The one use for a trader is as a benchmark: put a fixed-deposit rate in and see what your capital would earn doing nothing, then decide whether the trading is worth it.
- This is the calculator that makes the case for time. Hold the rate steady and drag the years from 5 to 20 — the interest earned grows far faster than the years do.
- Use it for a lump-sum deposit or a single investment. If you are adding money every month, the SIP calculator is the right formula instead.
When to use it, and where to find it
- When comparing a fixed deposit against another use for the same money.
- When you want a realistic sense of what a one-time investment could be worth in a decade.
Try it — a short walkthrough
- 1Enter the principal and the yearsThis is a one-time amount, nothing added later. Time is the strongest lever here, so try a few durations.See this part in detail →
- 2Set an honest rateThe rate is your own assumption and is capped at 20% a year so projections stay believable.See this part in detail →
- 3Switch the compounding frequencyMove between Yearly, Half-yearly, Quarterly and Monthly and watch the effective yield rise above the headline rate.See this part in detail →
Every part of the page
In the order you meet them on screen, each with a close-up of the real thing. The numbers match the dots on the figure above.
Principal and Time
Principal is the one-time amount you invest at the start — nothing is added later. Time is how many years you leave it invested.
How — For a monthly-instalment plan use the SIP calculator instead; this one assumes a single deposit.
- Principal is the P and Time is the t in A = P × (1 + r/n)^(n×t).
- Time is the strongest lever here — doubling the years does far more than nudging the rate.
Annual Rate
The yearly return you assume, before compounding is applied. "Nominal" simply means the headline rate, e.g. 12% per year.
How — Try a lower rate too — it is your own assumption, and nobody guarantees it.
- Internally it is used as r ÷ 100 ÷ n for each compounding period.
Compounding frequency
How often the earned interest is added back to the balance so it can start earning too.
How — Switch between Yearly, Half-yearly, Quarterly and Monthly and watch the maturity value rise slightly at the same headline rate.
- Yearly = 1, Half-yearly = 2, Quarterly = 4, Monthly = 12. That number is the n in the formula.
- More frequent compounding always gives a slightly higher final amount.
Maturity Value
The total you would have at the end — your original money plus all the interest it earned.
How — Read the "total growth" line underneath as growth across the WHOLE period, not per year.
- A = P × (1 + r/n)^(n×t).
- Total growth = (A ÷ P − 1) × 100.
Principal, interest, effective yield
How the final amount splits between your own money and the interest, plus the REAL yearly return once compounding is counted.
How — Compare Effective Yield with the Annual Rate you typed — the gap is what compounding adds.
- Total interest = maturity value − principal.
- Effective yield = ((1 + r/n)^n − 1) × 100. e.g. 12% compounded monthly is really about 12.68% a year.
Reading the numbers
- Maturity value A = P × (1 + r ÷ n)^(n × t), where P is the principal, r the annual rate as a decimal, n the compounding periods per year and t the years.
- n is 1 for Yearly, 2 for Half-yearly, 4 for Quarterly and 12 for Monthly.
- Interest earned = A − P. Total growth % = (A ÷ P − 1) × 100, across the whole period rather than per year.
- Effective yield = ((1 + r ÷ n)^n − 1) × 100. At 12% compounded monthly this comes out around 12.68%.
- The principal is capped at Rs 1 crore, the rate at 20% a year and the period at 20 years. No charges, tax or inflation are applied.
What it does not do
- This is plain interest arithmetic on numbers you assume. It is not a forecast of any NEPSE stock, fund or deposit.
- It assumes the rate never changes and nothing is withdrawn. Real deposits get repriced and real investors take money out.
- Tax on interest and inflation are both ignored, so the real value at maturity is lower than the figure shown.
- For monthly contributions this formula is wrong — use the SIP calculator.